Market overview and structural significance of Direct Selling Establishments Market
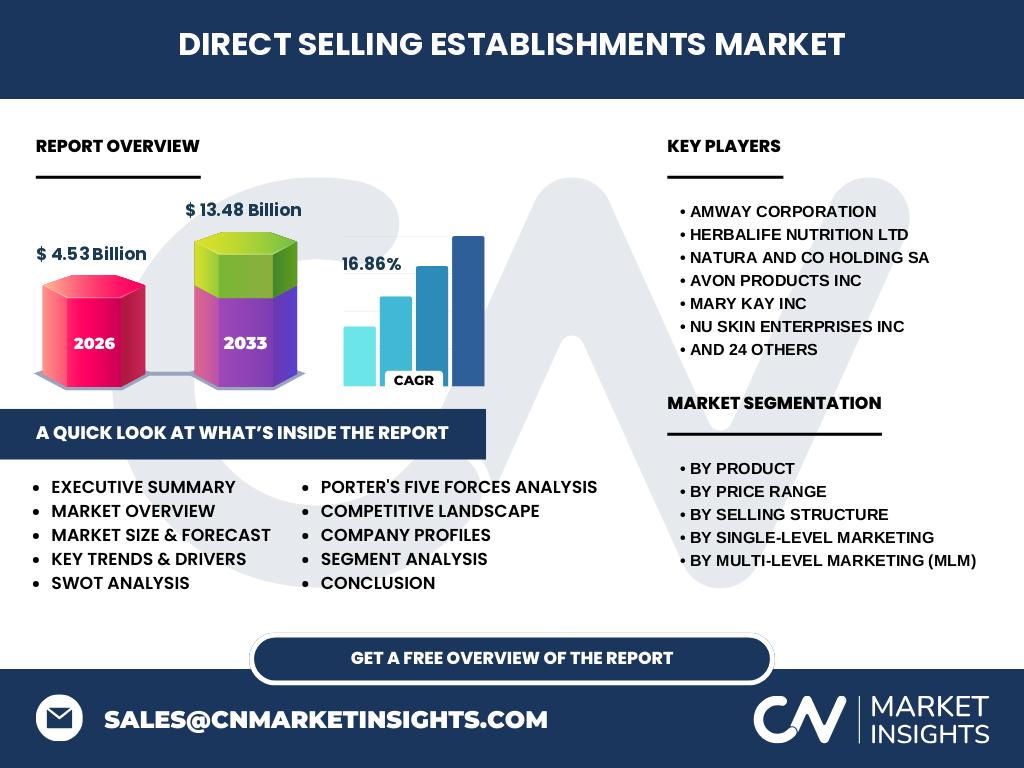
The Direct Selling Establishments Market represents a dynamic commercial ecosystem encompassing non-retail store channels where independent distributors market consumer goods. Valued at 4.53 Billion in 2026, this sector bypasses traditional wholesale intermediaries, leveraging personal networks, home demonstrations, and digital social selling. Regulatory oversight from bodies like the Direct Selling Association (DSA) heavily influences compliance across wellness and cosmetics portfolios globally.
Structural Growth Drivers and Market Restraints
Growth is propelled by rising demand for flexible micro-entrepreneurship and personalized Wellness and Cosmetics And Personal Care portfolios. Conversely, strict regulatory scrutiny regarding multi-level marketing (MLM) compensation structures by agencies like the FTC acts as a primary market restraint. Logistics bottlenecks in cross-border supply chains for nutritional supplements further challenge independent distributor margins.
Emerging Trends Reshaping Direct Selling Establishments Industry Trends
A definitive shift toward social commerce and livestreaming is redefining Direct Selling Establishments Market industry trends. Industry leaders are abandoning legacy offline recruitment in favor of data-driven digital funnels. Enhanced focus on clean-label ingredients in Wellness items aligns with modern consumer preferences for sustainable, ethically sourced personal care solutions.
Pandemic Impact and Post-Crisis Recovery Trajectory
The COVID-19 pandemic severely disrupted physical home parties and in-person catalog distribution. However, it catalyzed a rapid digital pivot toward virtual demonstrations and e-commerce integration. This structural adaptation accelerated recovery, positioning the market for an extraordinary expansion phase toward the 13.48 Billion valuation projected for 2033.
Competitive Benchmarking and Market Concentration
The competitive landscape features a mix of established giants like Amway Corporation, Herbalife Nutrition Ltd, and Natura and Co Holding SA alongside agile newcomers. Market concentration is moderately high among top tier multi-level marketing firms, which command significant share through sophisticated proprietary distributor compensation plans and robust global supply chains.
Executive Summary of Direct Selling Establishments Market Analysis
Our analysis indicates the Direct Selling Establishments Market is poised for explosive growth, expanding from 4.53 Billion in 2026 to 13.48 Billion by 2033 at a CAGR of 16.86%. This momentum is driven by digital transformation in affiliate marketing, robust demand for nutritional supplements, and expanding geographic footprints in emerging economies.
Long-Term Market Forecast from 2027 to 2033
Based on our econometric modeling, the Direct Selling Establishments Market market size will scale dramatically over the forecast period. Achieving a remarkable 16.86% CAGR from 2027 to 2033, the market will culminate in a 13.48 Billion valuation, heavily fueled by technological integration and increasing consumer adoption of Financial Services and Wellness offerings.
Segmentation Analysis Across Products and Selling Structures
Market segmentation spans multiple categories: Wellness, Cosmetics And Personal Care, Household Goods And Durables, Clothing And Accessories, Financial Services, Books, Toys, Stationery, Foodstuff And Beverages, and Other Products. Pricing ranges from Economy to Premium. Structures include Single-Level Marketing (retail, home parties, catalogs, personal selling) and Multi-Level Marketing (network marketing, affiliate programs, pyramid structures, compensation plans).
Regional Market Analysis and Geographic Distribution
Geographic performance varies significantly, with North America maintaining strong legacy revenues while Asia-Pacific emerges as the fastest-growing regional hub. Localized constraints, such as varying direct selling regulations in Southeast Asia and Latin America, require market participants to tailor their distributor compensation frameworks to ensure regional compliance and sustainable growth.
In-Depth Regional Review of High-Growth Territories
Asia-Pacific dominates incremental expansion, supported by dense urban populations receptive to social selling models. Latin America, anchored by firms like Betterware de Mexico SAPI de CV and Belcorp Corporation, demonstrates exceptional resilience in household goods and cosmetics penetration, navigating currency fluctuations through localized sourcing and flexible pricing strategies.
Company Profiles and Strategic Positioning
Industry leaders deploy distinct competitive strategies. Amway Corporation and Herbalife Nutrition Ltd focus heavily on science-backed Wellness portfolios. Meanwhile, Avon Products Inc and Mary Kay Inc leverage heritage brand equity in cosmetics. Digital-first innovators like Atomy Co Ltd utilize optimized affiliate structures to capture tech-savvy consumer segments across global markets.
Porter's Five Forces Assessment of the Sector
The industry experiences high competitive rivalry among established MLM networks. Supplier power remains moderate due to vertically integrated manufacturing by firms like Nu Skin Enterprises Inc and Melaleuca Inc. The threat of substitute products is subdued by strong brand loyalty fostered through personal selling and community-driven distributor networks.
SWOT Analysis of Direct Selling Establishments Market
Strengths include low startup barriers and strong peer-to-peer trust. Weaknesses involve high distributor churn rates. Opportunities lie in emerging digital affiliate frameworks and cross-border e-commerce expansion. Threats center on stringent regulatory crackdowns on multi-level compensation models by international consumer protection agencies.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material sourcing for Wellness and personal care formulations, passing through contract manufacturing and proprietary packaging. Finished goods flow directly to independent distributors via regional fulfillment hubs, bypassing traditional retail intermediaries before reaching end-consumers through personalized home demonstrations and digital platforms.
Investment Insights and High-Potential Opportunities
Investors should target enterprises integrating advanced digital affiliate marketing tools with high-margin Wellness portfolios. Companies demonstrating transparent compensation models and robust compliance frameworks present lower regulatory risk and superior long-term capital appreciation potential within the expanding 13.48 Billion market.
Conclusion and Strategic Key Takeaways
The Direct Selling Establishments Market is undergoing a digital renaissance. Transitioning from traditional door-to-door models to sophisticated social commerce ensures its trajectory toward 13.48 Billion by 2033. Stakeholders must prioritize regulatory compliance, technological agility, and product innovation to capture sustained value.
Research Methodology for Baseline Triangulation
Our baseline estimates are derived through rigorous data triangulation. We combine primary executive interviews with industry leaders, exhaustive trade registry data from global Direct Selling Associations, and secondary macroeconomic indicators regarding consumer discretionary spending to construct robust market models.
Scope of the Report and Coverage Parameters
This report covers global direct selling establishments across all major product categories, pricing tiers, and distribution structures from 2026 to 2033. Limitations include potential underreporting of informal micro-distributor transactions in developing economies and localized regulatory policy shifts occurring during the forecast window.
Recent Developments and Strategic Industry Moves
Recent strategic moves highlight accelerated digital transformation. Companies like Scentsy Inc and Young Living Essential Oils have launched enhanced mobile applications to streamline distributor onboarding. Meanwhile, partnerships between logistics providers and firms like USANA Health Sciences Inc aim to optimize cross-border fulfillment.